Close Menu
    What's Hot

    M&G Completes Bulk Purchase Annuity Transaction in Financial Services Industry

    September 14, 2026

    Editor’s Letter – Volume 2, Issue 9, September 2026

    September 9, 2026

    Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

    September 9, 2026
    X (Twitter) LinkedIn
    Longevity & Mortality Investor
    • Home
    • Coverage
      1. Life Insurance Capital Solutions
      2. Life Insurance
      3. Longevity and Mortality Risk Transfer
      4. Mortality
      5. Secondary Life Markets
      6. View All

      Pacific Life Re Executes First Asset-Intensive Reinsurance Transaction in Hong Kong

      September 9, 2026

      Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

      September 9, 2026

      New Report Suggests Global Life/Annuity Reinsurers Poised for Steady Growth

      August 27, 2026

      Pacific Life Re Completes Third Asset-Intensive Flow Reinsurance Transaction in Japan

      August 19, 2026

      US Individual Life Insurance Sales Continue Growth Trend in the Second Quarter

      August 13, 2026

      Shaping the Future of Health Insurance Through Innovation and Analytics

      June 10, 2026

      Q&A: Dr Christoph Schmitt, Director, Insurance, Fitch Ratings

      May 28, 2026

      Chronic Disease Onset and Cumulative Exposure: Clinical, Prognostic and Underwriting Implications

      May 13, 2026

      M&G Completes Bulk Purchase Annuity Transaction in Financial Services Industry

      September 14, 2026

      Slowing US PRT Market Sees Insurers Jostling for Business as Buy-Ins Surge

      September 9, 2026
      Just Group

      Just Group Completes Bulk Purchase Annuity Buy-In for Manufacturing Firm

      September 5, 2026

      Clara-Pensions Adds New Pension Scheme to Clara Pension Trust

      September 3, 2026

      Record Low Mortality Rates So Far in England and Wales in 2026

      July 9, 2026

      Organ Transplant Improvements Test Life Expectancy Assessment Models

      July 8, 2026

      The Pursuit of Everlasting Life Unlikely to Shift Actuarial Models

      June 10, 2026

      Pricing in the Unknown: Why Mortality Models Aren’t Ready for MCED Tests Just Yet

      April 9, 2026

      Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

      September 9, 2026

      AM Best Requests Comments on Proposed Revisions to Life Settlement Securitisation Criteria

      September 9, 2026
      Litigation

      Litigation Update: Wells Fargo Bank, N.A. v. Ameritas Life Insurance Corp

      August 26, 2026

      The Royal Society of Chemistry Pension Scheme Completes Bulk Purchase Annuity Buy-in With PIC

      August 13, 2026

      M&G Completes Bulk Purchase Annuity Transaction in Financial Services Industry

      September 14, 2026

      Editor’s Letter – Volume 2, Issue 9, September 2026

      September 9, 2026

      Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

      September 9, 2026

      Pacific Life Re Executes First Asset-Intensive Reinsurance Transaction in Hong Kong

      September 9, 2026
    • Events
    • Latest Issues

      Editor’s Letter – Volume 2, Issue 9, September 2026

      September 9, 2026

      Editor’s Letter – Volume 2, Issue 8, August 2026

      August 12, 2026

      Editor’s Letter – Volume 2, Issue 7, July 2026

      July 8, 2026

      Editor’s Letter – Volume 2, Issue 6, June 2026

      June 10, 2026

      Editor’s Letter – Volume 2, Issue 5, May 2026

      May 13, 2026
    • Contact Us
    Newsletter
    Longevity & Mortality Investor

    Life Settlements Portfolio Construction – Art or Science?

    Secondary Life Markets December 14, 2022By Beat Hess and Gabriel Maeder
    Portfolio Construction
    Share
    Twitter LinkedIn Email

    The concept of a life settlement investment is quite simple: the collected death benefits must exceed the cost (purchase price, premium payments, fees, etc.). A positive balance pays back to investors their initial investment and delivers a positive return once the initial investment has been paid off.

    The dimensions of life settlements – life expectancy, age of insured, gender, projected premium streams – are unlike any other asset, so constructing a life settlement portfolio comes with a different set of challenges than other asset classes.

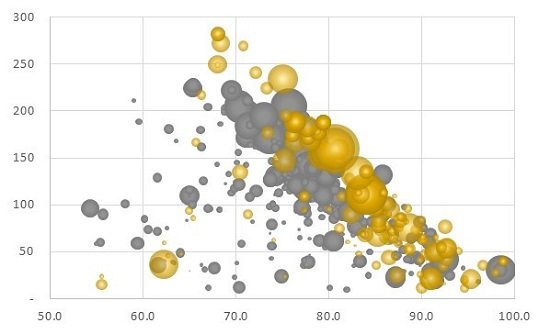
    Figure 1 below shows a section of life settlement deal flow. The age of the insured persons [years, x-axis] is as low as 50 and goes up to close to 100 years. The life expectancy estimates [months, y-axis] reflect age, gender, and health of the insured persons. The size of the policies relates to the size of the dots. Policies referring to male insureds have grey dots, policies referring to female insureds have yellow dots.

    The universe of available policies is rich. Each policy represents a unique combination of the various dimensions. And there is plenty of paper available in the secondary market (buying directly from the original owner) as well as the tertiary market (buying from other investors).

    Figure. 1: Offered policies, July to November 2020
    The accuracy of used life expectancies

    The main issue in life settlement investing is that the accuracy of the life expectancy estimates is uncertain. The face amounts do not necessarily come due when they should (according to the obtained life expectancies). Consequently, the future cashflows are uncertain, which is a challenge since the premium payments are crucial to keep the policies in force. An investor can tie up higher cash reserves in order to deal with this uncertainty, but a higher cash reserve detracts from the performance.

    The accuracy of the life expectancies is linked to other issues. There is still no requirement and/or standard for the medical underwriters to disclose the accuracy of their life expectancy estimates. Furthermore, the information for a transaction is provided by the sell side. The interest of the sell side is to achieve the highest possible price for a given policy, which depends ultimately on the life expectancy of the individual – the shorter the life expectancy, the higher the achievable price. The non-alignment of interest in combination with the information asymmetry between the sell side and the buy side overlays every engagement. This challenge needs to be carefully considered and dealt with by investors.
    The key to success

    History teaches us lessons; this is as true for life settlements as it is for any other asset class. It is therefore important to review and understand information regarding previous life settlement investments in order to avoid the mistakes of the past.

    When it comes to the physical investment, it is all about the accuracy of life expectancy estimates and risk management. The importance of knowhow about the accuracy of life expectancy estimates cannot be overstated – this element was a dominant driver behind the investment results in the past and it will be the most important factor for investments today and in the future. And the accuracy of life expectancy estimates is linked to risk management. The absence of thorough information about the accuracy of life expectancies makes it hard to establish a robust risk management overlay.

    The accuracy of life expectancy estimates, and the risk management challenges are combined and visualised in Monte-Carlo simulations, as can be seen in Figure 2, below. This is a great tool to help understand the capabilities of an asset manager and how an investment could perform. The chart illustrates that life settlements can be a great addition to a well-diversified portfolio – if done properly.

    Figure 2: Monte-Carlo Simulation of a Life Settlement Portfolio
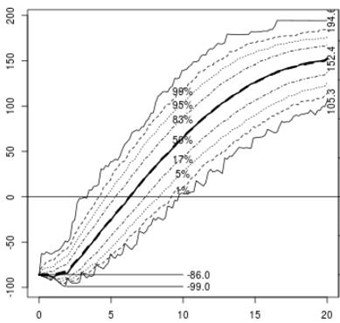
    The investment starts with an initial USD $86 million for the acquisition of the portfolio. The repayment of the initial investment is achieved via excess cash from collected death benefits over expenses (premium payments, fees etc.) after about seven years. Further excess cash leads to a positive return for investors. The bold line in the middle indicates the 50% probability under the assumption that the life expectancy estimates are correct overall. The other lines give an idea of the stochastic behaviour of the portfolio, i.e., the 83%/ 17% net cashflow probabilities assuming no longevity, and so forth.

    It is not a challenge to buy policies – the markets are there, and investors can help themselves. The challenge is to buy policies which ultimately allow the investor to collect more cash from death benefits than they pay in premiums and fees. This is the art of life settlement investing.

    Beat Hess is a Founding Partner and Gabriel Maeder is a Partner at AA-Partners

    Any views expressed in this article are those of the author(s) and do not necessarily reflect the views of Life Risk News or its publisher, the European Life Settlement Association
    2022 - December Commentary Life Settlements Longevity Risk Volume 1 Issue 8 - December 2022
    Share. Twitter LinkedIn Email

    Related Posts

    Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

    September 9, 2026By Greg Winterton

    AM Best Requests Comments on Proposed Revisions to Life Settlement Securitisation Criteria

    September 9, 2026By LMI Newsdesk

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026By Mark McCord
    Litigation

    Litigation Update: Wells Fargo Bank, N.A. v. Ameritas Life Insurance Corp

    August 26, 2026By Greg Winterton
    Latest Issue

    Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

    September 9, 2026

    Slowing US PRT Market Sees Insurers Jostling for Business as Buy-Ins Surge

    September 9, 2026

    Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

    September 9, 2026

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026
    Ad

    Where Longevity and Mortality Meet the Markets
    ISSN 2978-5219

    X (Twitter) LinkedIn
    Coverage
    • Life Insurance Capital Solutions
    • Life Insurance
    • Longevity and Mortality Risk Transfer
    • Mortality Risk
    • Secondary Life Markets
    More Info
    • Home
    • About Us
    • Contact Us
    • Guest Articles
    • Submit Story Idea
    Our Newsletter
    Get the latest industry news, commentary and events from the Longevity & Mortality Investor directly into your inbox. Why not sign up today?

    © 2026 Longevity & Mortality Investor. Website by Kavells.
    • Sitemap
    • Privacy Policy
    • Copyright Notice
    • Terms & Conditions

    Type above and press Enter to search. Press Esc to cancel.