Close Menu
    What's Hot

    Talcott Financial Group Closes Reinsurance Transaction with Lincoln Financial

    October 5, 2026

    InEvo Re Completes Two Further UK Reinsurance Transactions

    October 5, 2026
    Milliman

    Competitive US Pension Risk Transfer Cost Increases During August

    October 1, 2026
    X (Twitter) LinkedIn
    Longevity & Mortality Investor
    • Home
    • Coverage
      1. Life Insurance Capital Solutions
      2. Life Insurance
      3. Longevity and Mortality Risk Transfer
      4. Mortality
      5. Secondary Life Markets
      6. View All

      Pacific Life Re Executes First Asset-Intensive Reinsurance Transaction in Hong Kong

      September 9, 2026

      Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

      September 9, 2026

      New Report Suggests Global Life/Annuity Reinsurers Poised for Steady Growth

      August 27, 2026

      Pacific Life Re Completes Third Asset-Intensive Flow Reinsurance Transaction in Japan

      August 19, 2026

      US Individual Life Insurance Sales Continue Growth Trend in the Second Quarter

      August 13, 2026

      Shaping the Future of Health Insurance Through Innovation and Analytics

      June 10, 2026

      Q&A: Dr Christoph Schmitt, Director, Insurance, Fitch Ratings

      May 28, 2026

      Chronic Disease Onset and Cumulative Exposure: Clinical, Prognostic and Underwriting Implications

      May 13, 2026

      Talcott Financial Group Closes Reinsurance Transaction with Lincoln Financial

      October 5, 2026

      InEvo Re Completes Two Further UK Reinsurance Transactions

      October 5, 2026
      Milliman

      Competitive US Pension Risk Transfer Cost Increases During August

      October 1, 2026

      Arco Group Pension and Life Assurance Scheme To Transfer to Clara-Pensions

      September 30, 2026

      Record Low Mortality Rates So Far in England and Wales in 2026

      July 9, 2026

      Organ Transplant Improvements Test Life Expectancy Assessment Models

      July 8, 2026

      The Pursuit of Everlasting Life Unlikely to Shift Actuarial Models

      June 10, 2026

      Pricing in the Unknown: Why Mortality Models Aren’t Ready for MCED Tests Just Yet

      April 9, 2026
      European Life Settlement Association

      European Life Settlement Association Announces New Executive Committee Members for 2027

      October 1, 2026

      Abacus Global Management Completes Life Settlement Securitisation

      September 28, 2026

      The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

      September 23, 2026
      Litigation

      Litigation Update: U.S. Bank National Association v. Pacific Life Insurance Company

      September 23, 2026

      Talcott Financial Group Closes Reinsurance Transaction with Lincoln Financial

      October 5, 2026

      InEvo Re Completes Two Further UK Reinsurance Transactions

      October 5, 2026
      Milliman

      Competitive US Pension Risk Transfer Cost Increases During August

      October 1, 2026
      European Life Settlement Association

      European Life Settlement Association Announces New Executive Committee Members for 2027

      October 1, 2026
    • Events
    • Latest Issues

      Editor’s Letter – Volume 2, Issue 9, September 2026

      September 9, 2026

      Editor’s Letter – Volume 2, Issue 8, August 2026

      August 12, 2026

      Editor’s Letter – Volume 2, Issue 7, July 2026

      July 8, 2026

      Editor’s Letter – Volume 2, Issue 6, June 2026

      June 10, 2026

      Editor’s Letter – Volume 2, Issue 5, May 2026

      May 13, 2026
    • Contact Us
    Newsletter
    Longevity & Mortality Investor

    Q&A: Philip Siller, Executive Chair and Co-CEO, BroadRiver Asset Management

    Secondary Life Markets March 8, 2023By Greg Winterton
    Life Risk News Q&A
    Share
    Twitter LinkedIn Email

    ELSA’s Master Agreement for Tertiary Transactions (MATT) was first published in 2019. Life Risk News’ Greg Winterton caught up with Philip Siller, Executive Chair and Co-CEO at BroadRiver Asset Management, to discuss the origins of the document and its most salient points.

    GW: Philip, BroadRiver, in its capacity as an ELSA member, was one of the firms involved in drafting the MATT in the first place. Why did ELSA and BroadRiver feel that some kind of standardised document was important for players in the life settlement’s tertiary market?

    PS: Standard documentation for recurring transactions is a critical tool for an efficient market. It saves time and it saves money. ISDA documentation for the derivative market and standardized mortgage and security agreements in the real estate and UCC markets are examples. We, and others, saw a similar need for tertiary life settlement transactions and BroadRiver’s general counsel led the working group that developed the MATT.

    GW: Prior to the invention of the MATT, investors would have had different agreements with different counterparties. How easy has it been to evolve away from that model to a single, industry-wide model, and does the MATT provide enough flexibility when dealing with counterparties with different requirements?
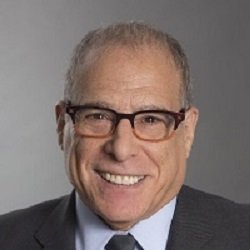
    Philip Siller

    PS: The transition to standardized documentation was surprisingly smooth, which was an endorsement of the care and objectivity of the working group. In my experience, the portions of contracts that eat up the most drafting time are not the business terms, but the allocation of risk terms. By focusing on an objective analysis of the allocation of risk – knowing that the members of the working group might be buyers one day and sellers the next – the working group drafted terms that followed the logic of a tertiary transaction. Almost immediately, the MATT was adopted by market actors.

    GW: Are there any knock-on advantages to using the MATT after the initial tertiary market transaction has been completed?

    PS: As the industry became more comfortable with the MATT, we discovered that post-closing issues could be resolved with less tension between the parties. Everyone understood that interpretations of the MATT that they were advancing as a buyer in one transaction would be read back to them next time when they were sellers. So, resolution of unexpected transaction glitches have gone smoother.

    GW: The MATT is a good example of standardisation in the life settlement market. Are there any other areas of the market, aside from transactions in the tertiary market, where you would like to see new or better standardisation?

    PS: My Co-CEO, Andrew Plevin and I started BroadRiver’s predecessor twenty years ago with the express purpose of attracting institutional investors to our funds. At that time, there was no consistency across provider documentation concerning even the most basic aspects of life settlements transactions, such as transfer of title and the role of providers versus funders. Broker/consumer contracts also took many forms. And, there were few law firms with expertise in the area.

    We understood that institutional investors could not transact in that environment. So, along with some of the institutions themselves (and Coventry, in particular), we worked to promote regulation to protect consumers and standardize transaction terms. At this point, there isn’t much more to do. The industry is well-regulated and contract terms are rarely a source of concern or delay in either the secondary or the tertiary markets.

    GW: Lastly, Philip, what tends to be the reaction of investors – your clients – when you discuss the MATT with them? I assume they’re pleased that firms like BroadRiver are attempting to usher the industry towards a more standardised, transparent transaction framework?

    PS: That’s correct. Our clients are diligent in understanding the execution risk around life settlement transactions. Earlier in the history of this asset class, this was an issue. It isn’t anymore.

    Philip Siller is Executive Chair and Co-CEO at BroadRiver Asset Management, L.P.
    2023 - March Life Settlements Longevity Risk Q&A Volume 2 Issue 3 - March 2023
    Share. Twitter LinkedIn Email

    Related Posts

    European Life Settlement Association

    European Life Settlement Association Announces New Executive Committee Members for 2027

    October 1, 2026By LMI Newsdesk

    Abacus Global Management Completes Life Settlement Securitisation

    September 28, 2026By LMI Newsdesk

    The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

    September 23, 2026By Greg Winterton

    Q&A: Beat Hess, Managing Partner, AA-Partners

    September 23, 2026By Greg Winterton
    Latest Issue

    Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

    September 9, 2026

    Slowing US PRT Market Sees Insurers Jostling for Business as Buy-Ins Surge

    September 9, 2026

    Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

    September 9, 2026

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026
    Ad

    Where Longevity and Mortality Meet the Markets
    ISSN 2978-5219

    X (Twitter) LinkedIn
    Coverage
    • Life Insurance Capital Solutions
    • Life Insurance
    • Longevity and Mortality Risk Transfer
    • Mortality Risk
    • Secondary Life Markets
    More Info
    • Home
    • About Us
    • Contact Us
    • Guest Articles
    • Submit Story Idea
    Our Newsletter
    Get the latest industry news, commentary and events from the Longevity & Mortality Investor directly into your inbox. Why not sign up today?

    © 2026 Longevity & Mortality Investor. Website by Kavells.
    • Sitemap
    • Privacy Policy
    • Copyright Notice
    • Terms & Conditions

    Type above and press Enter to search. Press Esc to cancel.