Close Menu
    What's Hot

    Talcott Financial Group Closes Reinsurance Transaction with Lincoln Financial

    October 5, 2026

    InEvo Re Completes Two Further UK Reinsurance Transactions

    October 5, 2026
    Milliman

    Competitive US Pension Risk Transfer Cost Increases During August

    October 1, 2026
    X (Twitter) LinkedIn
    Longevity & Mortality Investor
    • Home
    • Coverage
      1. Life Insurance Capital Solutions
      2. Life Insurance
      3. Longevity and Mortality Risk Transfer
      4. Mortality
      5. Secondary Life Markets
      6. View All

      Pacific Life Re Executes First Asset-Intensive Reinsurance Transaction in Hong Kong

      September 9, 2026

      Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

      September 9, 2026

      New Report Suggests Global Life/Annuity Reinsurers Poised for Steady Growth

      August 27, 2026

      Pacific Life Re Completes Third Asset-Intensive Flow Reinsurance Transaction in Japan

      August 19, 2026

      US Individual Life Insurance Sales Continue Growth Trend in the Second Quarter

      August 13, 2026

      Shaping the Future of Health Insurance Through Innovation and Analytics

      June 10, 2026

      Q&A: Dr Christoph Schmitt, Director, Insurance, Fitch Ratings

      May 28, 2026

      Chronic Disease Onset and Cumulative Exposure: Clinical, Prognostic and Underwriting Implications

      May 13, 2026

      Talcott Financial Group Closes Reinsurance Transaction with Lincoln Financial

      October 5, 2026

      InEvo Re Completes Two Further UK Reinsurance Transactions

      October 5, 2026
      Milliman

      Competitive US Pension Risk Transfer Cost Increases During August

      October 1, 2026

      Arco Group Pension and Life Assurance Scheme To Transfer to Clara-Pensions

      September 30, 2026

      Record Low Mortality Rates So Far in England and Wales in 2026

      July 9, 2026

      Organ Transplant Improvements Test Life Expectancy Assessment Models

      July 8, 2026

      The Pursuit of Everlasting Life Unlikely to Shift Actuarial Models

      June 10, 2026

      Pricing in the Unknown: Why Mortality Models Aren’t Ready for MCED Tests Just Yet

      April 9, 2026
      European Life Settlement Association

      European Life Settlement Association Announces New Executive Committee Members for 2027

      October 1, 2026

      Abacus Global Management Completes Life Settlement Securitisation

      September 28, 2026

      The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

      September 23, 2026
      Litigation

      Litigation Update: U.S. Bank National Association v. Pacific Life Insurance Company

      September 23, 2026

      Talcott Financial Group Closes Reinsurance Transaction with Lincoln Financial

      October 5, 2026

      InEvo Re Completes Two Further UK Reinsurance Transactions

      October 5, 2026
      Milliman

      Competitive US Pension Risk Transfer Cost Increases During August

      October 1, 2026
      European Life Settlement Association

      European Life Settlement Association Announces New Executive Committee Members for 2027

      October 1, 2026
    • Events
    • Latest Issues

      Editor’s Letter – Volume 2, Issue 9, September 2026

      September 9, 2026

      Editor’s Letter – Volume 2, Issue 8, August 2026

      August 12, 2026

      Editor’s Letter – Volume 2, Issue 7, July 2026

      July 8, 2026

      Editor’s Letter – Volume 2, Issue 6, June 2026

      June 10, 2026

      Editor’s Letter – Volume 2, Issue 5, May 2026

      May 13, 2026
    • Contact Us
    Newsletter
    Longevity & Mortality Investor

    Q&A: Sergey Jakimov, Founding Partner, LongeVC

    Mortality October 22, 2025By Greg Winterton
    Share
    Twitter LinkedIn Email

    The longevity economy is multi-faceted, with a range of investment opportunities available that can impact longevity in different ways. Greg Winterton spoke to Sergey Jakimov, Founding Partner of venture capital firm LongeVC, to get his views on both the space overall, and how LongeVC sees it, and therefore, approaches it. 

    GW: Sergey, let’s kick off with this: How does LongeVC actually define longevity? After all, you could make the argument that better urban design contributes to better longevity, but most would say that is real estate investing. 
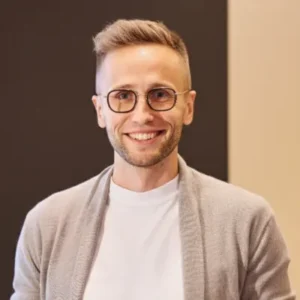
    SJ: It’s probably an over-used term but for us, it means a convergence of different types of technology, from traditional biotech to less traditional generative medicine; it’s the confluence of AI, engineering and healthcare, working together to prolong health span. As an investor, there are two approaches to longevity; one is to defeat aging, and the other is to defeat diseases. We’re in the second camp; health span should trigger ‘joy span’. At the end of the day, you want to have a life that is worth living so that you want to live longer. 

    GW: What qualities make a company a strong candidate for a longevity-focused investment? 

    SJ: Focus makes a good longevity company. There was something of a graveyard of capital 2019/2020 – when a lot of the talk was about fighting aging – because these companies never ended up with a therapy because they didn’t have a disease target. Fortunately, right now, you have a fairly consistent playbook of what it takes to arrive at patient outcomes in biotech. You need a disease indication so that you can design endpoints. You create success stories but then you need to be able to show accessible language. To lure more participants in, the longevity industry needs to start speaking the language of the capital providers – a ‘here’s how you can make money’ mindset. 

    GW: What areas of longevity do you believe are overhyped right now and why? 

    SJ: I’d say maybe reprogramming is a bit overhyped at the moment. You have these examples of technologies that have raised capital at tremendous valuations but that have still not delivered anything substantially; the investment case is more based on promise as opposed to interim data that is translatable to an investment case. Epigenetics and senolytics are probably as well. Getting rid of senescent cells may yield some results and improve overall well-being but the focus should be on disease-specific senescent cells. To be clear, I’m not saying that there is no applicability and promise in both of these areas; just that from an investment case perspective, I’m not sure either of these is quite there at the moment. 

    GW: Within the various sub-categories of longevity, what are one or two that are showing most promise in terms of being able to deliver sustainable companies? 

    SJ: It’s funny because it’s probably the two I mentioned that are over-hyped at the moment. In epigenetic reprogramming, it could be a case that for progress to be made, the first companies might have to die for the second companies to succeed; the latter takes the learnings from the first ones and improves on them, tightens the focus. Same with senescence. Once we figure out how to go after disease-related senescent-like cells, the frontier opens up. 

    GW: What role do you see policy and regulation playing in shaping the longevity market?  

    SJ: It is actually not very hard to understand the regulatory environment in biotech. It’s the same for everyone who is going after demonstrating results in living human beings; there is pre-clinical, an IND application, post clinical, etc. Agencies like the FDA are there because you need safety guardrails. I don’t think the regulatory landscape is as bad or complicated as people in the longevity field try to frame it. It‘s actually really easy; if you can demonstrate patient outcomes and understand and limit side effects, that’s a big piece of it for regulators.  

    What I would say on the policy side, though, is that in the US, grant cutting will have an impact. The funding cut made more spin-offs and more early-stage VCs become a greater share of the capital sources. That’s good because they have more ability to become an earlier-stage investor in a promising piece of science, and the supply of companies has grown as they need to source funding from somewhere other than the government. But the science is less mature as a result. 

    GW: Lastly, Sergey, what does the longevity investment landscape look like in 10 – 20 years and are there any adjacent fields (AI, robotics, space, etc.) that you think will increasingly intersect with longevity? 

    SJ: The answer is that I don’t know. In biotech, what is going to matter is the fusion of AI and robotics, where AI designs something and the result is fed into the AI to reinforce and learn from the outcomes, and then continue in the iterative loop. This is being done already and in 10 years a significant portion of drug discovery is going to be done this way. 

    And then, I think regenerative therapeutics will take their place in the whole spectrum of treatments. I think it’s still going to be age-related diseases. I wish I could say we’ll be into cryonics! But we need to crack age related diseases, maybe come up with how to use regenerative therapeutics to reduce chronic conditions. These treatments could provide tremendous relief to healthcare systems. 
    Sergey Jakimov is Founding Partner at LongeVC 

    2025 - November Longevity Risk Mortality Risk Q&A Volume 1 Issue 2 – November 2025
    Share. Twitter LinkedIn Email

    Related Posts

    The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

    September 23, 2026By Greg Winterton

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026By Mark McCord
    Litigation

    Litigation Update: Wells Fargo Bank, N.A. v. Ameritas Life Insurance Corp

    August 26, 2026By Greg Winterton

    Q&A: Mitchell Schepps, Senior Managing Director, Aon

    August 26, 2026By Greg Winterton
    Latest Issue

    Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

    September 9, 2026

    Slowing US PRT Market Sees Insurers Jostling for Business as Buy-Ins Surge

    September 9, 2026

    Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

    September 9, 2026

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026
    Ad

    Where Longevity and Mortality Meet the Markets
    ISSN 2978-5219

    X (Twitter) LinkedIn
    Coverage
    • Life Insurance Capital Solutions
    • Life Insurance
    • Longevity and Mortality Risk Transfer
    • Mortality Risk
    • Secondary Life Markets
    More Info
    • Home
    • About Us
    • Contact Us
    • Guest Articles
    • Submit Story Idea
    Our Newsletter
    Get the latest industry news, commentary and events from the Longevity & Mortality Investor directly into your inbox. Why not sign up today?

    © 2026 Longevity & Mortality Investor. Website by Kavells.
    • Sitemap
    • Privacy Policy
    • Copyright Notice
    • Terms & Conditions

    Type above and press Enter to search. Press Esc to cancel.