Close Menu
    What's Hot

    The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

    September 23, 2026
    Litigation

    Litigation Update: U.S. Bank National Association v. Pacific Life Insurance Company

    September 23, 2026

    Q&A: Beat Hess, Managing Partner, AA-Partners

    September 23, 2026
    X (Twitter) LinkedIn
    Longevity & Mortality Investor
    • Home
    • Coverage
      1. Life Insurance Capital Solutions
      2. Life Insurance
      3. Longevity and Mortality Risk Transfer
      4. Mortality
      5. Secondary Life Markets
      6. View All

      Pacific Life Re Executes First Asset-Intensive Reinsurance Transaction in Hong Kong

      September 9, 2026

      Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

      September 9, 2026

      New Report Suggests Global Life/Annuity Reinsurers Poised for Steady Growth

      August 27, 2026

      Pacific Life Re Completes Third Asset-Intensive Flow Reinsurance Transaction in Japan

      August 19, 2026

      US Individual Life Insurance Sales Continue Growth Trend in the Second Quarter

      August 13, 2026

      Shaping the Future of Health Insurance Through Innovation and Analytics

      June 10, 2026

      Q&A: Dr Christoph Schmitt, Director, Insurance, Fitch Ratings

      May 28, 2026

      Chronic Disease Onset and Cumulative Exposure: Clinical, Prognostic and Underwriting Implications

      May 13, 2026

      US Pension Risk Transfer Transactions Up, Aggregate Premium Down in Second Quarter

      September 21, 2026
      Just Group

      Engineering Council Pension Scheme Completes Bulk Purchase Annuity Buy-Out With Just Group

      September 16, 2026

      Special Melted Products Pension Scheme Completes Bulk Purchase Annuity Transaction With Canada Life

      September 15, 2026

      M&G Completes Bulk Purchase Annuity Transaction in Financial Services Industry

      September 14, 2026

      Record Low Mortality Rates So Far in England and Wales in 2026

      July 9, 2026

      Organ Transplant Improvements Test Life Expectancy Assessment Models

      July 8, 2026

      The Pursuit of Everlasting Life Unlikely to Shift Actuarial Models

      June 10, 2026

      Pricing in the Unknown: Why Mortality Models Aren’t Ready for MCED Tests Just Yet

      April 9, 2026

      The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

      September 23, 2026
      Litigation

      Litigation Update: U.S. Bank National Association v. Pacific Life Insurance Company

      September 23, 2026

      Q&A: Beat Hess, Managing Partner, AA-Partners

      September 23, 2026

      Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

      September 9, 2026

      The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

      September 23, 2026
      Litigation

      Litigation Update: U.S. Bank National Association v. Pacific Life Insurance Company

      September 23, 2026

      Q&A: Beat Hess, Managing Partner, AA-Partners

      September 23, 2026

      US Pension Risk Transfer Transactions Up, Aggregate Premium Down in Second Quarter

      September 21, 2026
    • Events
    • Latest Issues

      Editor’s Letter – Volume 2, Issue 9, September 2026

      September 9, 2026

      Editor’s Letter – Volume 2, Issue 8, August 2026

      August 12, 2026

      Editor’s Letter – Volume 2, Issue 7, July 2026

      July 8, 2026

      Editor’s Letter – Volume 2, Issue 6, June 2026

      June 10, 2026

      Editor’s Letter – Volume 2, Issue 5, May 2026

      May 13, 2026
    • Contact Us
    Newsletter
    Longevity & Mortality Investor

    Life, Health-Based InsurTech Pulls Back Again in 2023: Outlook Uncertain

    Life Insurance January 10, 2024By Greg Winterton
    Share
    Twitter LinkedIn Email

    Last year was one that many in the alternative investment industry would like to forget. Fundraising and deal activity fell significantly as investors rotated to liquid credit opportunities due to the relatively better yield offered by these products, along with a perceived lower risk when benchmarked against a more volatile geopolitical climate. 

    For those in the venture capital industry, add the collapse of Silicon Valley Bank in March and the resulting fallout amongst the start-up ecosystem, and you have something of an annus horribilis for the VC folks. 

    The venture capital-backed life insurance insurtech market certainly took a hit. According to data from PitchBook, through Q3 2023, the number of deals completed was just 26, less than half of the total for 2022 and only 25% of the total for 2021, and the total value of those deals was just $0.22bn, a fifth of the total observed in the previous year and down significantly from 2021’s banner year of $3.71bn. 

    Source: PitchBook Data, Inc. 

    Comparing activity in 2023 to prior full years isn’t quite an apples-to-apples comparison, because the data for last year only goes through the first three quarters; it’ll be another couple of months until the full year data for 2023 becomes available. But, unless the fourth quarter of last year delivers extraordinary numbers, it’s clear that 2023 will end up delivering a significant pull back. 

    Indeed, the life and health segment of insurtech that PitchBook tracks wasn’t the only segment that took a hit last year. All other segments were off when compared to 2022, with the industry globally halving in terms of deal value from almost $9bn in 2022 to $4.05bn in 2023 and the overall number of deals falling from 670 to 366. 
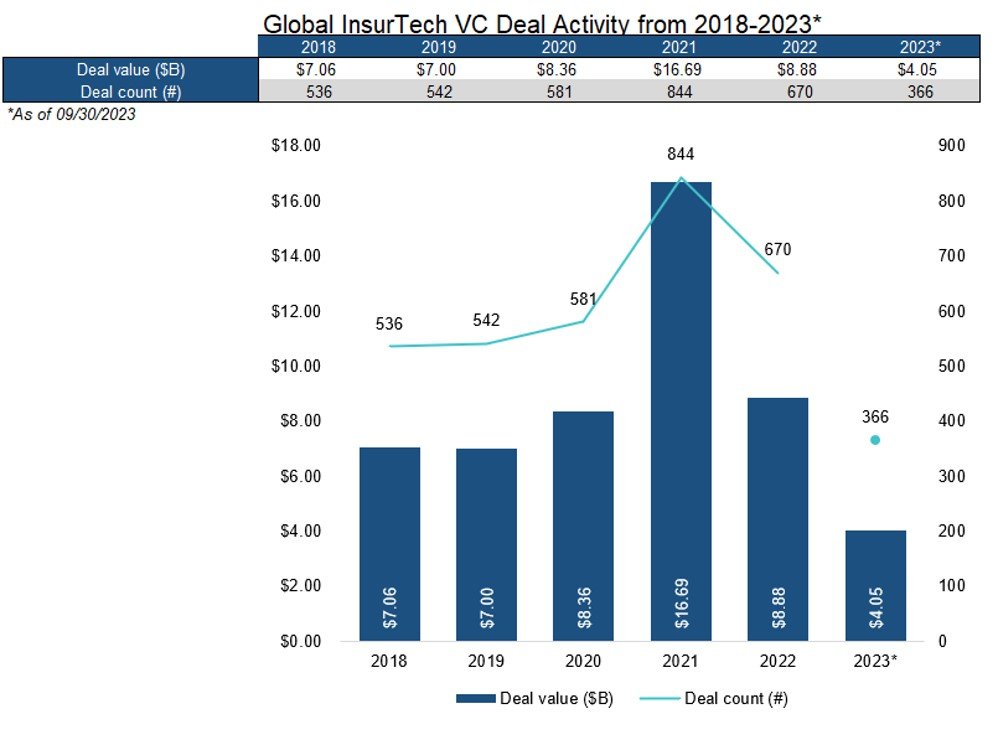
    Source: Pitchbook Data, Inc. 

    What’s notable for the life and health segment is that aggregate deal value reduced by more than the average. Keith Raymond, Principal Analyst, Insurance, at Celent, says that differences between how and why life insurance is purchased might be contributors to why VCs shied away from the space last year. 

    “High interest rates impact consumer spending by reducing discretionary dollars. Consumers must buy home and auto insurance to buy a house or a car, but they don’t need to buy life insurance,” said Raymond. 

    “And life solutions are generally more complex both from a product and a process perspective and can often require an agent or a relationship to navigate the purchase. P&C insurance is transactional and can mostly be done direct to consumer, and can also leverage some investments made in banking, which from a process standpoint is also transactional. VCs likely wanted to invest more defensively in 2023 than in previous years.” 

    That’s not all. Robert Le, Senior Emerging Technology Analyst at PitchBook, adds that there are factors idiosyncratic to the space which have impacted activity – or a lack thereof. 

    “For the most part there hasn’t been a lot of innovation in these areas. Early insurtech companies were able to convince investors that their digital distribution will lead to cheaper CACs. But for the most part, consumers still wanted to speak to a human when making health and life insurance buying decisions. This is evident in that most life insurtech companies have reverted to employing human agents over the past couple of years,” he says.  

    The S&P 500 delivered returns of approximately 24% in 2023, a significant increase that saw the index end last year close to all-time highs. Increasing investor confidence, as indicated by a rising public equity environment, and a plateauing interest rate regime might see 2024 return to growth in terms of venture capital fundraising as investors rotate back into illiquid assets, providing more ammunition to VCs looking to invest in the next insurtech unicorn. 

    “Based on both anecdotes (conversations with founders and investors) and data trends, we believe VC funding may have already bottomed out, and we expect an uptick in Q4 and increased funding in 2024. The publicly traded insurtech companies have recovered a bit in 2023, so that will lead to more bullish sentiment for the vertical in 2024,” says Le. 

    But that increased bullishness will not necessarily translate directly into a boomerang-style rebound in insurtech activity this year. There has certainly been an increase in the understanding of what works in the insurtech space in the past 18-24 months and there has also been something of an emergence of winners – or not – as well. This maturation of the segment has made VCs take a more cautious approach to the due diligence process, impacting deal activity. These trends means that, for Raymond, any increase in insurtech activity this year is unlikely to mirror the resurgent public equity market in the US. 

    “It’s true that various macroeconomic factors, including inflation and rising interest rates, coupled with market apprehensions and a constriction of liquidity in both public and private markets, have steered toward a pronounced correction in insurtech generally,” he says. 

    “But skepticism may linger among investors, particularly concerning the scalability and profitability of new technological integrations, which would steer them towards a more conservative approach toward insurtech for the foreseeable future.” 
    2024 - January Life Insurance Insurtech Longevity Risk Mortality Risk Volume 3 Issue 1 - January 2024
    Share. Twitter LinkedIn Email

    Related Posts

    The Structural Decision for Setting Up a Life Settlement Vehicle in Ireland

    September 23, 2026By Greg Winterton

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026By Mark McCord
    Litigation

    Litigation Update: Wells Fargo Bank, N.A. v. Ameritas Life Insurance Corp

    August 26, 2026By Greg Winterton

    Q&A: Mitchell Schepps, Senior Managing Director, Aon

    August 26, 2026By Greg Winterton
    Latest Issue

    Awareness Raising is More Than Just a One-Month Campaign for Life Settlement Market

    September 9, 2026

    Slowing US PRT Market Sees Insurers Jostling for Business as Buy-Ins Surge

    September 9, 2026

    Bermuda Life & Annuity Sidecar Market Quadruples as Alternative Asset Manager/Life Insurance Convergence Continues

    September 9, 2026

    Insurers Sweeten Bulk Purchase Annuity Offers as Buy-Out Timetables – and Costs – Look Set To Increase

    August 26, 2026
    Ad

    Where Longevity and Mortality Meet the Markets
    ISSN 2978-5219

    X (Twitter) LinkedIn
    Coverage
    • Life Insurance Capital Solutions
    • Life Insurance
    • Longevity and Mortality Risk Transfer
    • Mortality Risk
    • Secondary Life Markets
    More Info
    • Home
    • About Us
    • Contact Us
    • Guest Articles
    • Submit Story Idea
    Our Newsletter
    Get the latest industry news, commentary and events from the Longevity & Mortality Investor directly into your inbox. Why not sign up today?

    © 2026 Longevity & Mortality Investor. Website by Kavells.
    • Sitemap
    • Privacy Policy
    • Copyright Notice
    • Terms & Conditions

    Type above and press Enter to search. Press Esc to cancel.